

Natural Resource Partners (NRP)
Soda Ash
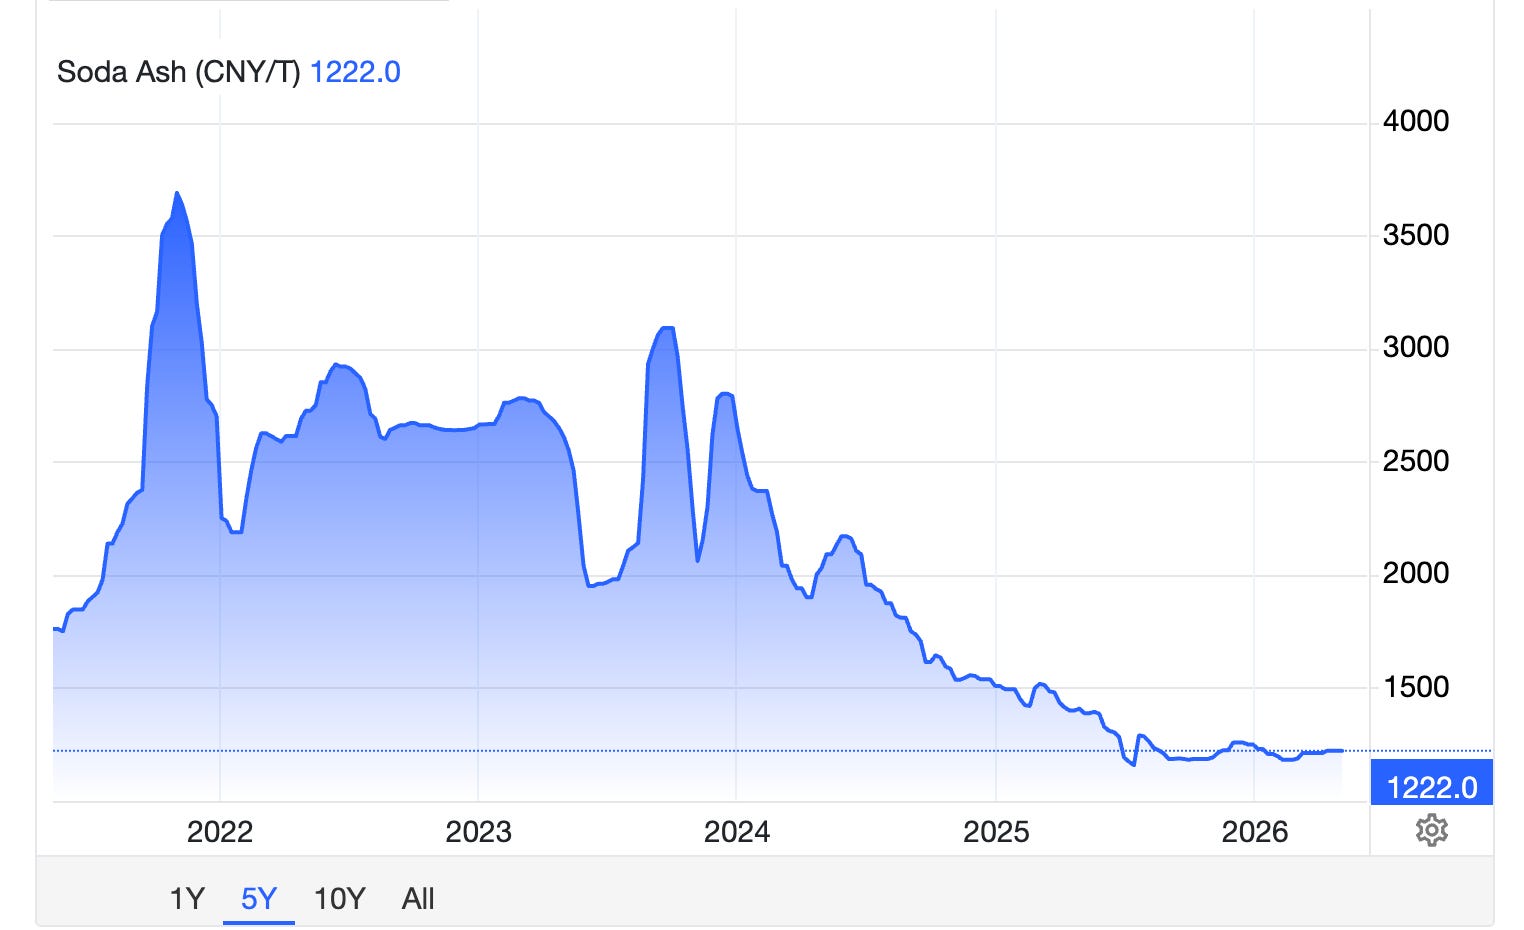
NRP had an unusually tough quarter because of its soda ash business. Prices are below the cost of production for most producers, driven by a supply glut from China and weak demand for flat glass.
Last quarter, NRP said that they would inject $39.2 million equity into its Sisecam Wyoming JV. The managing partner wanted to reduce debt in light of the cyclical downturn in soda ash pricing. This quarter that transaction materialized in the financial statements.
Collectively, NRP and its partner (Sisecam Chemicals Wyoming LLC) invested $80.0 million into Sisecam Wyoming. The full $80 million was used to pay down the JV’s bank credit facility. $60 million of debt remains; $29.4 million is NRP’s pro rata share.
NRP’s free cash flow was -$5.4 million and gross debt increased from $33 to $60 million. Since the quarter ended, net debt has been reduced to $45 million.